Real Estate Law / Ontario
Property taxes, rebates and non-resident transactions
Buying or selling an Ontario property, reviewing a tax notice or checking a rebate? We help you understand the legal requirements, document obligations and timing, and coordinate connected tax advice.
Legal services provided by a lawyer licensed in Ontario.
- Clear advice
- Practical next steps
- Steady guidance
Identify the tax, the transaction and the people involved
Different rules can use different definitions of a first-time buyer, resident or owner. An exemption or rebate under one program does not establish eligibility under another.
I am buying, transferring or reviewing a rebate
Transfer taxes, HST wording or a proposed rebate affect the transaction budget.
I have a property tax or assessment concern
An assessment, classification, bill or decision needs the correct review route.
My status may affect a purchase
Foreign-buyer restrictions, speculation taxes or an exemption need assessment before committing.
A seller may be non-resident for tax purposes
Clearance, withholding and closing arrangements need early attention.
Legal review with the right supporting advice
We confirm the legal work included. Tax calculations, returns, accounting, valuations and broader Canadian or foreign tax planning may need separate professional advice or engagements.
Understand transfer taxes and any available refund
A purchase price is only part of the budget. The transfer, ownership interests and available relief need to be assessed before closing.
Ontario and Toronto requirements
We review land transfer tax issues for the proposed transaction, including the interest acquired, consideration, assumed obligations and any applicable exemption. Toronto has its own municipal land transfer tax in addition to Ontario’s tax. A transfer without a stated purchase price, or a change involving family members, should not be assumed to be tax-free.
First-time buyer refunds
Ontario and Toronto refund requirements need separate consideration. Previous ownership, a spouse’s ownership, citizenship or permanent-resident status, occupancy and the applicable dates may affect a claim. Being a first-time buyer under a federal program does not automatically establish entitlement to a land transfer tax refund.
Ownership changes and beneficial interests
Adding or removing an owner, changing shares or dealing with a beneficial interest can raise tax and reporting questions beyond registration of a transfer. We assess the legal requirements alongside the actual arrangement and identify connected accounting or tax advice. A nominal payment or informal understanding does not determine the tax treatment.
Confirm the closing documents and budget
We address relevant registration statements, supporting evidence and refund documentation within the engagement. Tell us about all purchasers, ownership history and intended use before the documents are finalized. A potential future refund should not be treated as available closing funds until eligibility and the claiming process are confirmed.
Choose the right route for a property tax concern
Separate the assessment from the tax bill
The Municipal Property Assessment Corporation (MPAC) assesses and classifies Ontario properties; the municipality issues the property tax bill. An issue with assessed value, classification, a municipal adjustment or a billing entry may need a different response. Provide the actual notice or bill and explain what appears incorrect.
Reconsideration requests and appeals
We assess the relevant process, evidence and deadlines, including whether a Request for Reconsideration is required before an Assessment Review Board appeal. The property class, notice and type of complaint matter. Where retained within scope, we can assist with the legal submissions and representation; valuation evidence may require an appropriate professional.
Municipal adjustments and transaction accounts
A cancellation, reduction, refund or other municipal relief request has its own grounds and requirements; it is not the same as challenging an assessment. Property tax arrears, supplementary or omitted bills and closing adjustments can also affect a transaction. We review the relevant legal issues and documents. A challenge does not, by itself, suspend payment obligations or extend a filing date.
Vacancy and ownership-related obligations
Municipal vacancy taxes and declarations must be checked separately for the municipality and ownership year. The federal Underused Housing Tax no longer requires returns or tax for 2025 and later years, but unresolved obligations for 2022–2024 may still need attention. We identify relevant legal issues and coordinate any required accounting or filing advice rather than assume that an exemption under one system answers every question.
Connect HST and housing rebate terms with the actual use
An advertised price or an estimated rebate does not settle the buyer’s entitlement or the parties’ obligations under the agreement.
Review what the price and contract include
We review HST provisions in purchase and assignment agreements, including whether tax is included, whether a rebate is credited or assigned to a builder, and who bears a shortfall if eligibility is not met. The contract terms, tax treatment and cash needed at closing must be considered together.
Identify the relevant housing rebate
New housing, first-time home buyer and new residential rental property rebates use different eligibility tests. Federal and Ontario components, including any enhanced rebate, need separate confirmation. Agreement, construction and ownership dates, price, ownership history, status and intended or actual occupancy can matter. A qualifying owner-occupied home and a rental property should not be treated as the same claim.
Address assignments and supporting documents
An assignment of a purchase agreement can raise its own HST and rebate questions. We review the documents and coordinate tax advice about the treatment, reporting, remittance and supporting records. Assignment of a purchase agreement and assignment of a rebate to the builder are different arrangements and need to be understood separately.
Keep the claim consistent with the facts
We assist with transaction-related rebate documentation within scope and identify information that needs confirmation. Tell us if the proposed occupants, ownership or intended use changes. A credit on a closing statement is not a guarantee of entitlement; a claim can be reviewed and an unsupported amount may need to be repaid. No rebate amount or approval is promised before the requirements are assessed.
Review a buyer’s status before committing to a property
Distinguish the relevant status tests
Citizenship, immigration status and income tax residency are different concepts. A person’s passport, mailing address or time outside Canada does not answer every test. Companies, trusts and co-ownership arrangements can raise additional questions. We identify the legal requirements and coordinate tax or immigration advice where needed.
Check purchase restrictions and exceptions
We assess whether a federal restriction applies to the person, property and transaction date, including any relevant exception. A work or study permit should not, by itself, be treated as confirmation that a purchase is permitted. Paying a tax does not authorize a purchase that is otherwise restricted.
Consider speculation taxes separately
Ontario’s Non-Resident Speculation Tax and Toronto’s municipal non-resident speculation tax have their own application and relief requirements. They are separate from ordinary land transfer taxes and federal purchase restrictions. All buyers and ownership arrangements need review; a co-purchaser’s status can affect the transaction. An exemption from one rule does not establish relief from another.
Confirm evidence and the timing of any relief
We review the relevant declarations, status evidence and transaction documents within scope. A later change of status does not automatically produce a refund or rebate; the applicable program, ownership, occupancy and time requirements must be met. Financing, authority and signing arrangements also need confirmation before closing.
Plan for clearance, withholding and the sale proceeds
Non-resident sale requirements can affect both the seller and the purchaser. They should be addressed while the transaction is being planned.
Assess the seller’s tax-residency position
Canadian income tax residency is fact-dependent and can require tax-adviser input, including consideration of residential ties and any relevant treaty. Canadian citizenship does not, by itself, establish residency for these purposes. Tell us about a planned move or change in circumstances before the transaction documents and closing arrangements are settled.
Address section 116 requirements
A disposition of taxable Canadian property by a non-resident can engage Income Tax Act notification, certificate-of-compliance and purchaser-withholding requirements. The property type, any exclusion or certificate and the transaction details matter. We review the legal closing requirements and coordinate the required tax work; a residency statement alone is not a substitute for the necessary inquiry and documents.
Understand a holdback’s effect on available funds
Where withholding or a holdback is required, funds may need to remain available for remittance rather than be released to the seller. The amount can be based on sale proceeds rather than the gain and can differ from the final tax liability. This can affect mortgage payouts and the seller’s available closing funds. We address the appropriate documents, responsibilities and release conditions; a pending application does not automatically eliminate the purchaser’s exposure.
Separate clearance from the final tax result
A certificate of compliance does not necessarily complete all of the seller’s tax obligations or determine the final tax on the transaction. Returns, calculations, refunds or other filings may still need the appropriate tax adviser. We confirm the work included and coordinate documents and timing; clearance, release of a holdback or an extension of closing cannot be guaranteed.
Meet our principal lawyer
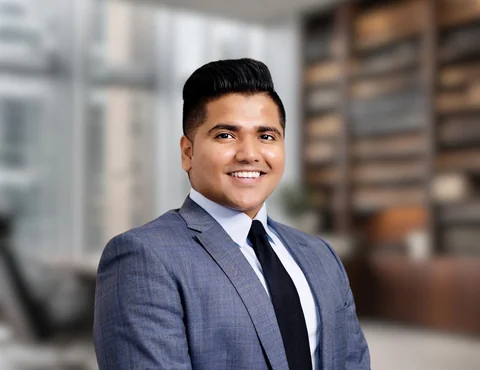
Vinay Thapliyal
Founder & Principal Lawyer
Licensed to practise law in Ontario
Vinay’s practice includes Ontario real estate matters. Legal Route helps clients understand the legal documents, status questions and transaction obligations, and coordinates with accountants and other advisers where connected analysis is needed.
Meet Vinay ThapliyalTell us about the property and the issue
A brief description is enough to start. Please wait for secure sharing instructions before sending tax records, status documents or other confidential material.
What to tell us
- Your role and the parties
Say whether you are a buyer, seller, owner or authorized representative, and name the parties for a conflict check.
- The property and the question
Identify the Ontario municipality, property type and the tax, rebate, assessment or status issue you want reviewed.
- The stage and intended use
Say whether an agreement is signed, a notice has arrived or a claim is pending, and describe the intended occupancy or use briefly.
- Dates and connected advisers
Identify known closing, claim, payment or review dates and any accountant, tax adviser or other professional already involved.
Consultation, fees and scope
Fees depend on the documents, transaction or dispute stage, complexity and assistance requested. We confirm any consultation fee before booking and explain proposed legal fees, taxes and anticipated expenses before retention.
Government taxes, filing or registration charges, searches, appraisals, accounting and other professional work may involve additional costs or separate engagements. We confirm which legal work is included.
Keep the first inquiry brief. We will explain how to share agreements, notices, assessment records, rebate documents, residency information and correspondence securely.
How engagement begins
Understand the issue and stage
We check conflicts, availability, your role and the legal help requested.
Confirm scope and fees
We explain any consultation fee before booking, define responsibilities and arrange secure document sharing.
Carry out the agreed legal work
Once retained, we review the documents and requirements and coordinate connected professional work as needed.
Property tax, rebate and residency questions
Does being a first-time buyer qualify me for every refund or rebate?
No. Land transfer tax refunds and housing rebate programs use different tests. Previous ownership, a spouse’s ownership, status, use and relevant dates can matter in different ways. We assess the applicable program and supporting facts rather than assume that eligibility under one scheme carries across to another.
Is a transfer between family members automatically tax-free?
No. Consideration, assumed obligations, ownership interests, the type of transfer and any applicable exemption need review. Broader income tax consequences may require tax-adviser input. Tell us the proposed arrangement before documents are signed or an ownership change is registered.
Is my property assessment the same as my property tax bill?
No. MPAC’s assessment and classification and the municipality’s bill serve different functions. The right response depends on what is disputed and the notice received. A reconsideration request, assessment appeal and municipal adjustment or relief request are not interchangeable.
Does an HST rebate credit in the agreement guarantee I qualify?
No. The agreement can allocate the financial consequences if the requirements are not met. We review the relevant terms and transaction-related documentation, and coordinate tax advice where needed. The actual program, occupants, intended use and dates must support the claim; no rebate is guaranteed by a contract label or closing credit.
Can a non-Canadian buy if they are willing to pay the extra tax?
Tax payment and permission to purchase are separate questions. We check whether purchase restrictions apply and whether an exception is available, alongside provincial or municipal speculation taxes and other transfer taxes. A permit, co-purchaser or claimed exemption needs assessment under the particular rule.
Does Canadian citizenship establish that a seller is resident for tax purposes?
Not by itself. Income tax residency depends on the relevant facts and may need tax-adviser analysis. A seller’s residency position and the applicable non-resident sale requirements need attention early, even if the seller has a Canadian passport or previously lived in the property.
Is a non-resident sale holdback the seller’s final tax bill?
Not necessarily. The closing withholding or holdback requirements and the final tax calculation serve different purposes. A certificate of compliance and any further return, refund or payment need consideration. We confirm the legal closing scope and coordinate the appropriate tax work; a pending certificate does not automatically permit funds to be released.
Can I arrange this work while elsewhere in Ontario or outside Canada?
Suitable consultations, document review and coordination can be virtual. We confirm authority, identification, time zones and any signing, lender, registration or attendance requirements. Assessment proceedings and cross-border documents may need separate arrangements. Legal Route’s office is in Brampton, and clients elsewhere can inquire about an Ontario matter.
Serving clients across Ontario
Virtual appointments available · In-person appointments in Brampton
From our Brampton office, we assist clients with Ontario property tax, rebate and non-resident transaction matters across Toronto and the GTA regions of Peel, York, Halton and Durham, as well as elsewhere in Ontario.
Suitable consultations, document review and coordination can be virtual, including where a participant is outside Canada. We confirm authority, identification, time zones and any signing, lender, registration or attendance requirements. Proceedings, foreign documents and connected tax advice may need separate arrangements.
Ontario communities we serve
Our Brampton office assists with Ontario property tax, rebate and non-resident transaction matters in these and other communities.
Toronto includes North York, Scarborough and Etobicoke.
Peel Region includes Brampton, Mississauga and Caledon.
York Region examples include Vaughan, Markham, Richmond Hill, Aurora and Newmarket.
Halton Region includes Oakville, Burlington, Milton and Halton Hills.
Durham Region examples include Pickering, Ajax, Whitby, Oshawa, Clarington and Uxbridge.
Elsewhere in Ontario, examples include Hamilton, Guelph, Kitchener-Waterloo, Cambridge, Barrie, London, Windsor, Kingston, Ottawa and Greater Sudbury. You can inquire from other Ontario cities, towns and townships.
Tell us where the property is, your role, the issue and any date that needs attention. These community examples describe our service reach; our physical office is in Brampton.
This page provides general legal information, not advice for your circumstances. Sending an inquiry does not, by itself, create a lawyer-client relationship or confirm acceptance of your matter or deadline.