Real Estate Law / Ontario
Private mortgages and secured lending
Before you borrow or lend against Ontario property, understand the terms, the security and the plan for repayment. We advise private borrowers or lenders on the documents, risks and legal steps for their transaction.
Legal services provided by a lawyer licensed in Ontario.
- Clear advice
- Practical next steps
- Steady guidance
Which side of the transaction are you on?
Start with your role, the property and what has already been agreed or signed.
I am borrowing from a private lender
You have a proposed commitment or loan and want to understand the cost, obligations and repayment terms.
I am lending against a property
You need advice on the borrower, the mortgage security and the conditions for advancing your funds.
I am changing or renewing a mortgage
You need to review an extension, assignment, amendment or the arrangements at maturity.
Agree on the legal work you need
We identify our client and assess conflicts and independent representation requirements before accepting the matter.
Understand the borrowing terms before you commit
The interest rate is only part of the cost. A private mortgage can involve lender and brokerage fees, deductions from the advance and a short term that leaves the principal due at maturity.
Compare the loan amount with the money available
We review the commitment and related documents to explain interest, repayment, fees and conditions. We check how deductions, existing mortgage payouts and other closing costs affect the funds you expect to receive.
- The gross loan, any interest reserve (funds held back to cover interest) and the expected net proceeds.
- Payment dates, interest-only terms and whether payments reduce the principal.
- Prepayment rights, minimum interest, early repayment charges and discharge costs.
- Default provisions, renewal conditions and any further security or guarantee.
Plan for the maturity date
If the principal remains owing at the end of the term, you need a workable way to repay it. We explain the legal repayment obligations and review any proposed renewal or extension. Financing options and suitability should also be discussed with your licensed mortgage professional or other appropriate adviser.
Missing payments or failing to repay at maturity can put the property at risk. Depending on the documents and circumstances, the lender may take enforcement steps, including selling the property.
If you have already signed, tell us what you signed and when. We review the existing obligations and any remaining conditions before advising on the next step.
Check the security before advancing funds
A registered mortgage gives security over identified property. Its usefulness depends on the documents, the property and the claims that may rank ahead of it.
Identify the parties, property and priority
We review the proposed borrower, registered ownership, authority to sign and the intended security. Title searches help identify existing mortgages and other registered interests. A second or subsequent mortgage needs particular attention to prior debt and the terms affecting priority.
Align the documents with the loan
The commitment, loan agreement, mortgage and any guarantee serve different purposes. We prepare or review the agreed documents, the conditions for advancing funds and any priority or postponement agreement needed between lenders.
- Who owes the debt and who is providing the property or other security.
- The amount, interest, payment terms, maturity date and permitted use of funds.
- Existing charges, required payouts, insurance and other closing conditions.
- Reporting, repayment and the steps required to release or transfer the mortgage.
Property valuation and the borrower’s ability to repay need their own assessment. A title search or mortgage registration does not establish market value or guarantee repayment. Tell us how the loan was arranged so we can identify any licensing or disclosure questions that require review.
Document the people and promises behind the loan
A loan involving a family member, a corporation or a property seller still needs clear terms and an assessment of who can represent each person.
Vendor take-back mortgages
When a seller finances part of the purchase price, the purchase agreement and mortgage terms need to work together. We review the amount left owing, payments, maturity, other financing and the seller’s intended security as part of the agreed transaction.
Corporate and family lending
Identify whether the borrower and lender are individuals or corporations, who owns the property and who will sign. Written documents help clarify whether money is a loan, when it must be repaid and what security is intended. Corporate authority and related-party arrangements may require additional review.
Personal and corporate guarantees
A guarantee can create liability beyond the mortgaged property, depending on its terms. We review any limit, continuing obligations, demand provisions and proposed changes. A guarantor may need independent legal advice or representation.
Confirm representation early
Borrowers, lenders, property owners and guarantors can have different interests. We assess the applicable rules and conflicts before agreeing to act. Separate lawyers may be required; consent alone does not resolve every restriction on representing more than one party.
Carry the agreed terms through closing and maturity
A proposed funding date depends on complete instructions, documents, cleared funds and satisfied conditions. Signing a commitment does not by itself complete the mortgage.
Signing, funds and registration
For the party we represent, we coordinate the agreed closing work, including identity and authority checks, execution requirements, searches and registration. We explain the conditions that must be met before funds can be released and what closing report or registered documents will follow.
Renewals, extensions and amendments
Check the written terms before assuming the lender will renew. A proposed extension can change interest, fees, repayment or security. We review the existing documents and the proposed changes, including any consent or further documentation needed from an owner, guarantor or other lender.
Assignments and repayment
If the mortgage is being transferred to a new lender, we review the assignment, authority and related documents within the agreed scope. When a loan is being paid out, the amount owing and the release of the registered charge require coordination. Our mortgage payouts and discharges service explains that work.
Meet our principal lawyer
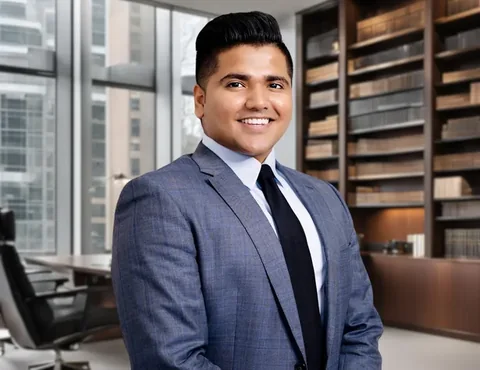
Vinay Thapliyal
Founder & Principal Lawyer
Licensed to practise law in Ontario
Vinay’s practice includes real estate transactions and financing. Legal Route helps private lending clients understand the obligations, security and legal steps involved in their proposed transaction.
Meet Vinay ThapliyalTell us about the loan and your role
A short description is enough for the first inquiry. You do not need to upload your loan documents to get started.
What to tell us
- Your role and the parties
Tell us whether you are the borrower, lender, owner, seller or guarantor, and name the other parties for a conflict check.
- The property and loan
Identify the Ontario municipality, the proposed lending amount and whether a first or subsequent mortgage is involved.
- The documents and help needed
Say whether there is a proposed or signed commitment, a guarantee, an existing mortgage or a proposed change.
- The dates that matter
Tell us the commitment expiry, funding or maturity date and whether any payment demand or default notice has arrived.
Consultation, fees and scope
Fees depend on the documents, complexity and agreed assistance. We confirm any consultation fee before booking and explain proposed legal fees, taxes and anticipated expenses before retention.
Commitment review, lender documentation, independent advice and a mortgage closing can involve different work. The lender and brokerage can confirm their own fees and charges.
Please wait for secure sharing instructions before sending commitments, account or banking details, identification or signed documents.
How engagement begins
Check parties and representation
We assess conflicts, whom we can represent, availability and the dates involved.
Confirm advice, scope and fees
We arrange any consultation and confirm the documents and legal work included in the engagement.
Begin the agreed work
Once retained, we review or prepare documents and coordinate the agreed advice, negotiation or closing steps.
Private mortgage questions
Do you advise both private lenders and borrowers?
We accept inquiries from either side. Before taking a matter, we identify our client and assess conflicts, the rules on borrower and lender representation and any independent advice requirements. Separate lawyers may be needed. We do not promise to represent everyone in the same transaction.
Should I get legal advice before signing a commitment?
It is useful to have the proposed commitment reviewed before you sign because it can create binding obligations. If you have already signed, tell us when and which documents are involved so we can review the existing terms and remaining conditions.
Does registering a second mortgage guarantee the lender will be repaid?
No. Prior claims, the property’s value, the debt and enforcement costs can affect recovery. We review the proposed security and priority; registration does not remove the financial risk of lending.
Can a private mortgage secure a loan between family members?
A family loan can be documented and secured against property where appropriate. The parties should clarify whether the advance is a loan, the repayment terms and the intended security. Ownership, existing financing and representation requirements still need review.
What should a guarantor have reviewed?
The review should address the debt being guaranteed, any limit, continuing liability, demand provisions and the effect of later loan changes. The terms can expose assets beyond the mortgaged property. We confirm whether independent advice or separate representation is required.
Will my private mortgage renew automatically?
Do not assume it will. The existing documents and any written renewal agreement govern. Review the maturity date, new interest or fees and repayment obligations early, together with your plan to repay or obtain replacement financing.
What do you need with my first inquiry?
A brief description of your role, the parties, the property’s Ontario municipality, the proposed loan and any important date is enough to begin. Wait for secure sharing instructions before sending confidential documents or identification.
Can you help if the property or a party is outside Brampton?
We assist with Ontario property transactions from our Brampton office. Document review and meetings can often be virtual. We confirm where each person is signing and any lender, identity, independent advice or execution requirements before arranging the closing.
Serving clients across Ontario
Virtual appointments available · In-person appointments in Brampton
From our Brampton office, we advise private borrowers or lenders on Ontario property transactions across Toronto and the GTA regions of Peel, York, Halton and Durham, as well as elsewhere in Ontario.
For suitable matters, we can review commitments, discuss loan terms and meet with you virtually. Closing arrangements depend on lender instructions, the parties’ locations and the identity, authority, signing and independent advice requirements for the transaction.
Ontario communities we serve
Our Brampton office serves Ontario property owners, borrowers and lenders in these and other communities.
Toronto includes North York, Scarborough and Etobicoke.
Peel Region includes Brampton, Mississauga and Caledon.
York Region examples include Vaughan, Markham, Richmond Hill, Aurora and Newmarket.
Halton Region includes Oakville, Burlington, Milton and Halton Hills.
Durham Region examples include Pickering, Ajax, Whitby, Oshawa, Clarington and Uxbridge.
Elsewhere in Ontario, examples include Hamilton, Guelph, Kitchener-Waterloo, Cambridge, Barrie, London, Windsor, Kingston, Ottawa and Greater Sudbury. You can inquire from other Ontario cities, towns and townships.
Tell us where the property is, your role and the proposed funding or maturity date. These community examples describe our service reach; our physical office is in Brampton.
This page provides general legal information, not advice for your circumstances. Sending an inquiry does not, by itself, create a lawyer-client relationship or confirm acceptance of your matter or deadline.