Real Estate Law / Ontario
Mortgages, refinancing and home equity borrowing
A refinance, lender switch or home equity loan can change what is registered on title and which debts must be paid at closing. We review your mortgage documents and coordinate the legal steps for your financing.
Legal services provided by a lawyer licensed in Ontario.
- Clear advice
- Practical next steps
- Steady guidance
Which financing step are you preparing for?
Start with the loan you have, the financing you’re considering and the next date you need to meet.
I’m refinancing or switching lenders
You want to know what must happen to the old mortgage and what the new lender requires.
I’m borrowing against my home
You’re considering a line of credit, second mortgage or another type of secured borrowing.
My financing involves another person or a title change
You’re adding or removing an owner, arranging a guarantee or checking who needs to sign.
Agree on the legal work you need
We confirm whom we can represent and which work we can take on once we know the lender, the parties and the proposed date.
Know what changes when you refinance or switch lenders
Start with your current mortgage and the new lender’s terms. We review the legal documents, what needs to happen to the existing mortgage and what the new lender requires before funding.
Renewal, lender switch or refinance
A renewal with the same lender can often be handled directly with that lender. A switch can involve transferring the existing mortgage or paying it out and registering a new one. The steps depend on how the current mortgage is registered, what debts it secures and what the lenders require.
A refinance may change the amount you borrow or the terms of the loan. If you end your mortgage early, check whether a prepayment charge applies. We review how any payout, charge and other lender costs affect the closing figures.
Check the financing conditions and legal instructions
A financing commitment may come with conditions. The instructions sent to your lawyer can set out requirements for title, insurance, identification, signing or repayment of certain debts. We identify the legal steps and coordinate them within the agreed scope. Your lender decides on approval and sets the financing terms. Your mortgage broker can explain product options.
Understand what borrowing against your home secures
A home equity line of credit, or HELOC, lets you borrow and repay within your approved credit limit under the lender’s terms. It is secured by your home. A second mortgage adds another charge on title and typically ranks behind the first mortgage.
Read the security and repayment terms
We check which borrowing the charge secures, including linked accounts or future advances where the documents provide for them. We review repayment obligations, guarantees and what can happen if the terms are breached. Secured borrowing can put the property at risk if you default.
Check the existing mortgage before adding borrowing
If the first mortgage will stay in place, we review its terms and the title. The existing or incoming lender may require consent, an agreement about priority or other conditions. For financing through a private lender, see private mortgages and secured lending.
Flag financing with special terms or dates
Tell us if the financing is a reverse mortgage, a bridge loan between a purchase and sale, or a construction draw. The legal work can include reviewing repayment triggers, coordinating closing dates or confirming the registration conditions for an advance.
Check who owns the property and who needs to sign
We review title, the parties to the financing and the lender’s instructions. A proposed ownership change, guarantor or additional signer can affect the work and timing.
Confirm owners, borrowers and guarantors
Tell us who is on title, who is borrowing and whether anyone will guarantee the debt. If the property is a matrimonial home, we check whether spousal consent or another legal requirement applies. We also confirm whom we can represent and whether anyone needs independent legal advice or separate representation.
Raise an ownership or signing change early
Adding or removing an owner may require separate transfer documents, lender approval and a review of tax consequences. Tell us if someone will take over an existing mortgage or if the lender is asking to amend a registered charge. Let us know if someone will sign under a power of attorney or from outside Ontario. We can check what the lender and the transaction require for authority, identity verification and signing.
Follow the payouts, funds and registrations through closing
We explain how the new funds will be used and what you may need to provide or receive at closing. The final figures depend on the lender’s instructions, current payouts and transaction expenses.
Use a payout statement for the closing date
A payout can include accrued interest, fees or a prepayment charge in addition to the principal balance. We review the amount and the date it applies to, which accounts need to be repaid or closed, and any costs or shortfall you should plan for.
Coordinate registration, funding and discharge
Within the agreed scope, we coordinate signing and applicable registration, follow the lender’s instructions for funds and arrange any required payout or discharge steps. We explain when any funds can be released to you and what will be confirmed after closing.
Tell us if you only need a discharge
If you’re paying off secured borrowing without taking a new loan, tell us whether the lender has issued a payout or discharge document. We can confirm the separate work needed to deal with the existing charge, including a partial discharge where applicable.
Meet our principal lawyer
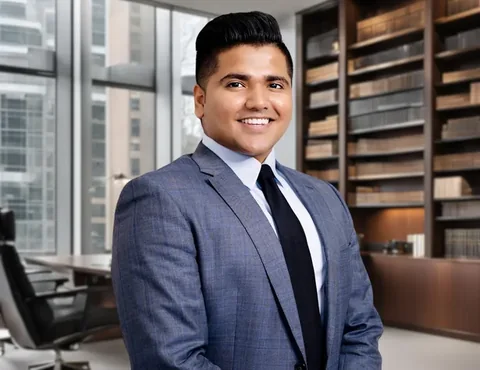
Vinay Thapliyal
Founder & Principal Lawyer
Licensed to practise law in Ontario
Vinay’s real estate practice includes property purchases, sales, refinancing and title work. Legal Route helps borrowers understand the lender’s legal requirements and the steps needed to close.
Meet Vinay ThapliyalTell us about your financing and timing
A short summary of the property, the financing and your next deadline is enough to start.
What to tell us
- The property and your role
Tell us the municipality, who owns the property and whether you’re an owner, borrower or guarantor.
- The financing you’re arranging
Tell us whether you’re refinancing, switching lenders or adding secured borrowing, and whether you have a commitment.
- Existing mortgages and any changes
Identify existing lenders and tell us if an owner, guarantor or other signer will change.
- Dates and instructions
Tell us the expected funding date, the mortgage maturity date if relevant and any deadline you’ve received.
Consultation, fees and scope
We confirm any consultation fee before booking. Before you retain us, we explain the proposed legal fees, taxes and anticipated expenses for the agreed work.
A document review, title transfer and financing closing can involve different work. We explain what’s included. Your lender can confirm its own charges.
Please wait for secure sharing instructions before sending loan statements, account numbers, identification or signed financing documents.
How engagement begins
Check the parties and dates
We confirm conflicts, availability and the lender or transaction details we need.
Confirm scope and fees
We identify the legal work, how separate advice or title changes fit and what we need from the lender.
Begin the agreed work
Once retained, we review the documents, confirm outstanding conditions and coordinate the agreed legal steps.
Questions about mortgages and refinancing
Does a mortgage renewal need a lawyer?
A straightforward renewal with the same lender can often be completed with that lender. If the lender, registered security, owners or other signing parties will change, tell us what the lender is asking you to sign.
What if my mortgage also secures a line of credit?
Some mortgage charges also secure a line of credit or another account. If you’re switching lenders, confirm which balances must be repaid and whether any accounts must be closed before the existing charge can be transferred or discharged.
Why is the payout higher than the balance I see online?
The payout can include interest through the proposed closing date and applicable lender fees or a prepayment charge. We review the payout statement and confirm whether the lender needs to update it if the closing date changes.
Can I add a HELOC or second mortgage and keep my first mortgage?
That depends on the existing mortgage terms and what both lenders require. We check the registered charges and whether consent, a priority agreement or another condition is required.
Can I add or remove someone from title during a refinance?
It may be possible with the lender’s approval and the appropriate transfer documents. We review the ownership and signing requirements and identify tax questions and any need for separate advice.
When can I receive the remaining refinance funds?
We first confirm that funding, registration and the lender’s release conditions are satisfied. The amount available depends on the advance, required payouts and transaction expenses. Tell us if you need the funds by a specific date.
What if the lender requests independent legal advice?
Tell us who is borrowing or guaranteeing the debt and share the lender’s exact request through our secure instructions. We check conflicts and confirm whether separate advice or representation is required.
Can you help if I’m outside Brampton?
We assist with Ontario property financing. Meetings and document review can often be arranged virtually. We confirm the lender’s identity and signing requirements and whether an in-person step is needed.
Serving clients across Ontario
Virtual appointments available · In-person appointments in Brampton
From our Brampton office, we assist with mortgage, refinancing and home equity transactions across Toronto and the GTA regions of Peel, York, Halton and Durham, as well as elsewhere in Ontario.
For suitable matters, we can review documents and meet with you virtually. Tell us where the property is and where each person will sign so we can confirm identification, lender and signing requirements.
Ontario communities we serve
Our office is in Brampton. We assist with Ontario mortgage and refinancing work in these and other communities.
Toronto: Toronto, including North York, Scarborough and Etobicoke.
Peel Region: Brampton, Mississauga and Caledon.
York Region: Vaughan, Markham, Richmond Hill, Aurora and Newmarket.
Halton Region: Oakville, Burlington, Milton and Halton Hills.
Durham Region: Pickering, Ajax, Whitby, Oshawa, Clarington and Uxbridge.
Elsewhere in Ontario: Hamilton, Guelph, Kitchener-Waterloo, Cambridge, Barrie, London, Windsor, Kingston, Ottawa, Greater Sudbury and other Ontario communities.
Tell us where the property is and where you’ll be when it’s time to sign.
This page offers general legal information. For advice about your circumstances, speak with a lawyer. We confirm representation, scope and timing separately after receiving an inquiry.